India’s Next Investor Wave Won’t Come From Mumbai, Delhi or Bengaluru
For years, when we talked about the narrative around investing in India, I think we unconsciously imagined a fairly familiar, traditional investor.
Someone sitting in a metropolitan city, actively focused on investing in India. Someone with a demat account, a mutual fund portfolio, a financial adviser, and perhaps a decent understanding of equities.
But that picture of investing in India is rapidly changing. The next big wave of people investing in India may not come from the traditional financial centres at all.
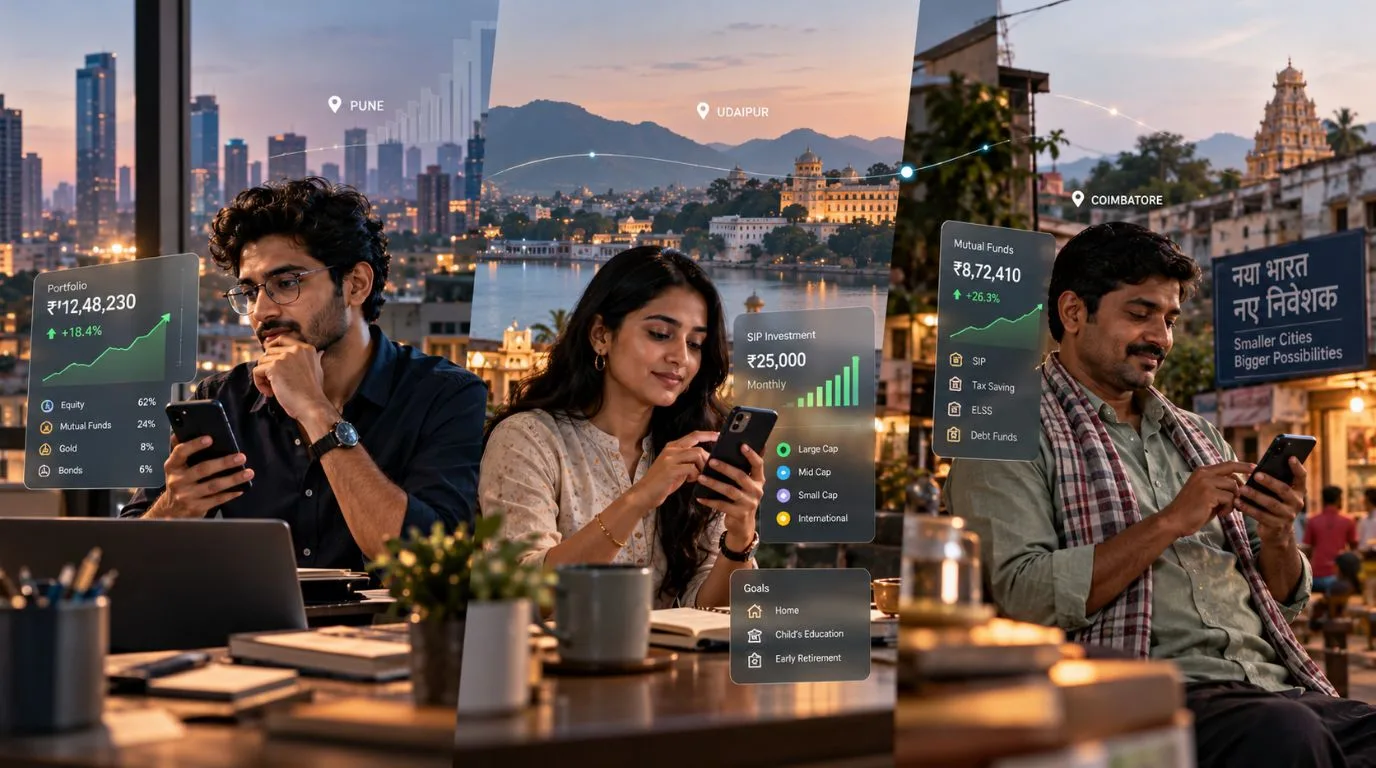
It may come from Tier-2 and Tier-3 cities, younger Indians, women, salaried households, and millions of people who are already comfortable using digital payments but haven’t yet started investing in India seriously.
That is the interesting message emerging from EY India’s latest report on wealth inclusion. EY estimates that the momentum behind investing in India could add more than 100 million long-term investors by 2035 and for me, that is a much bigger story than simply “more people are investing.”
India Has Solved Access. The Next Challenge Is Participation.
Look at the numbers shaping the future of investing in India. India has built an extraordinary digital financial infrastructure to support citizens investing in India. The EY report puts the number of active UPI users at more than 550 million, while the number of mutual fund investors is around 62 million and active equity market participants around 50 million.
That gap fascinates me when analyzing the landscape of investing in India. We have created a population that is extremely comfortable with digital money.
People who may never have walked into a bank branch regularly are perfectly comfortable scanning a QR code, transferring money instantly, and checking a transaction on their phone but investing in India is a different behaviour.
Using money digitally doesn’t automatically mean growing money digitally and that is where the next financial opportunity for investing in India could lie.
From Financial Inclusion To Wealth Inclusion
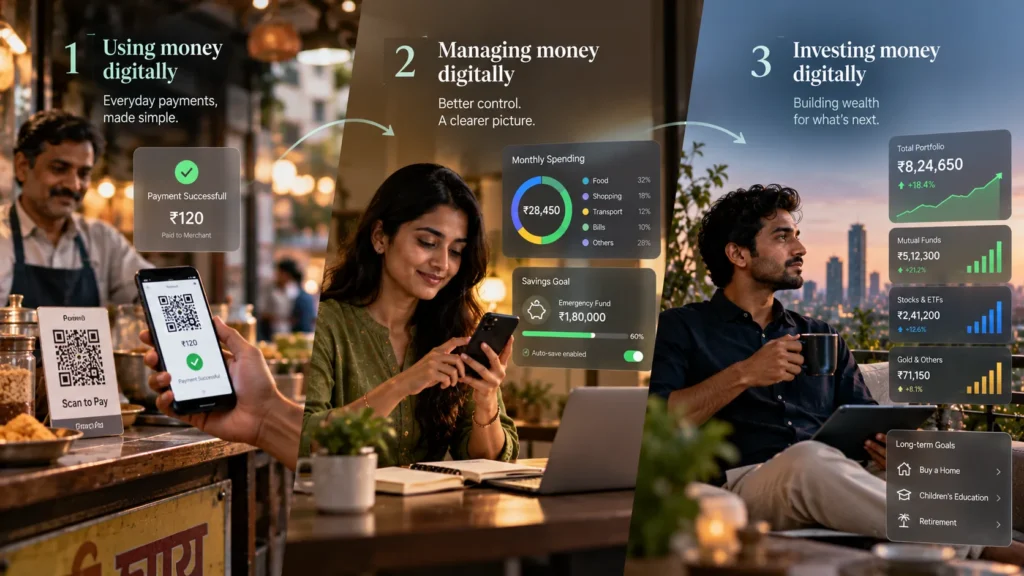
I think this is the most important shift in the story of investing in India. Financial inclusion was largely about getting people into the formal financial system:
- Bank account → Digital payments → Credit → Financial services
The next phase of investing in India is different:
- Savings → Investing in India → Compounding → Wealth creation
EY’s data shows that Indian household investable assets reached nearly US$5.2 trillion in FY25, while financial assets increased their share of total household assets from 28% in FY15 to around 35% in FY25.
That tells me something important about the collective mindset toward investing in India. India isn’t abandoning its traditional preference for physical assets overnight but the financialisation of household wealth through investing in India is clearly becoming more important.
The Investor Is Getting Younger
One of the numbers I find particularly interesting is the changing age profile of demographics investing in India. According to EY, investors under 30 accounted for around 38% of the investor base in June 2026, compared with 23% in FY19.
That is a substantial change for the demographic wave investing in India. The next generation of investors has grown up with:
- Smartphones
- UPI
- Digital banking
- Fintech apps
- Instant notifications
- Online financial content
- Easy account opening
For them, investing in India doesn’t necessarily begin with a relationship manager. It can begin with a mobile screen and that changes the entire customer journey for financial brands.
The Next Investor May Not Live In A Metro
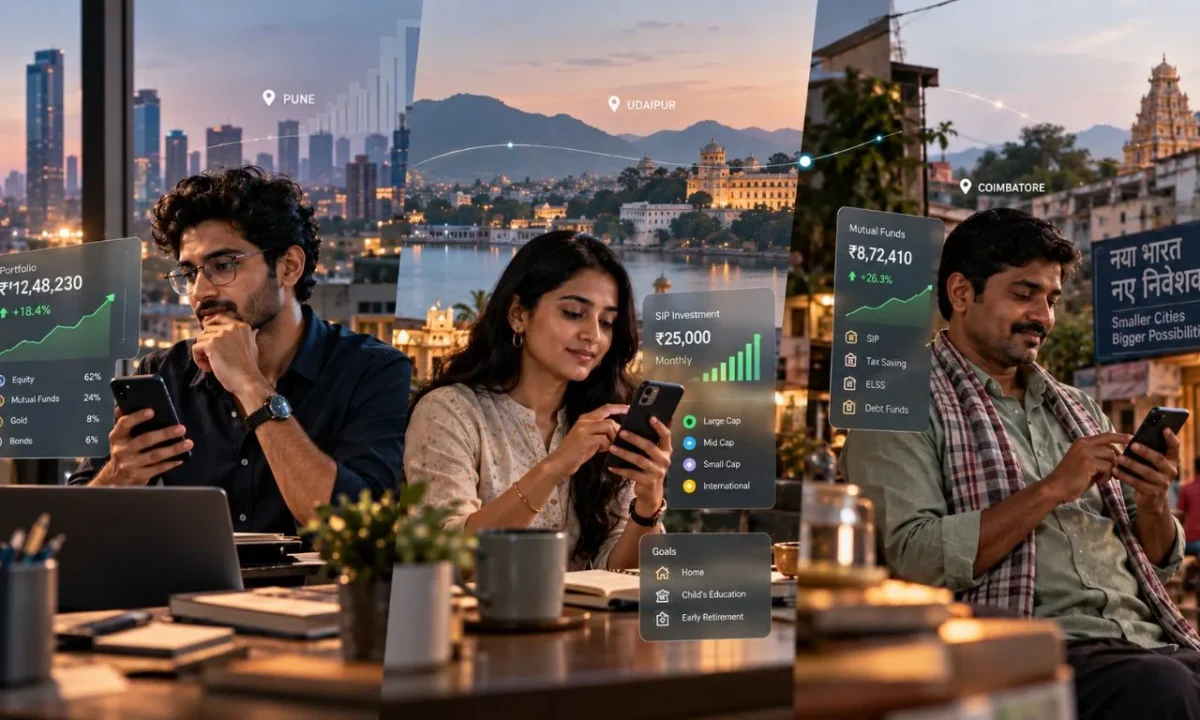
This is perhaps the most important marketing opportunity hidden inside the numbers for investing in India. EY says cities beyond India’s top 110 now contribute 12% of mutual fund AUM in FY25, while districts beyond the top 10 accounted for 70% of NSE-registered investors trading in FY25.
That changes the way financial services companies need to think about customer acquisition for investing in India. For decades, financial marketing was heavily concentrated around metropolitan India but the next wave of people investing in India could be sitting in:
- Indore.
- Jaipur.
- Coimbatore.
- Lucknow.
- Nagpur.
- Bhubaneswar.
- Surat.
- Patna.
- Or hundreds of smaller cities and towns.
And increasingly, that customer is digitally reachable.
Women Are Becoming A Bigger Part Of The Investment Story
Another shift I wouldn’t ignore is the growing participation of women investing in India.
EY reports that women accounted for 26% of unique mutual fund investors in December 2025, compared with 24% a year earlier. It also reports substantial growth in women’s mutual fund AUM, from US$54.3 billion in 2020 to US$178 billion in 2025. This is more than a demographic statistic for women investing in India.
It represents a potentially different audience for financial brands and I think there is a marketing lesson here:
Don’t simply create a financial product and then try to sell it to women. Create communication that recognises their actual financial journeys, aspirations, responsibilities, and specific questions about investing in India. The same principle applies to young investors and people outside metros.
The Big Problem Isn’t Access. It’s Confidence.
Here is where I think the story gets particularly interesting.
India has already built much of the infrastructure required to make investing in India accessible. The bigger challenge is:
“Do I understand what I’m doing?”
Investing in India can feel complicated. People worry about risk. They don’t understand terminology. They don’t know whether something is suitable for them.
They may start investing in India and stop when markets become volatile. So simply creating another investment app isn’t necessarily going to solve the problem.
EY’s report specifically highlights the importance of guidance, financial capability, and AI-enabled intelligence in converting digital access into sustained wealth creation and I think that’s the next battlefield.
Financial Brands Will Have To Become Better Educators
This is where my marketing brain kicks in.
Imagine the difference between saying: “Start your SIP today” and saying:
“Here’s how a ₹5,000 monthly investment works over 10, 15 and 20 years.”
The second communication teaches. The first one sells. For India’s next generation of investors, education may become one of the most powerful acquisition tools for investing in India.
- Short videos.
- Regional-language content.
- Interactive calculators.
- AI-powered explanations.
- Simple comparisons.
- Webinars.
- WhatsApp-based education.
- Personalised nudges.
The financial services brand that can make investing in India easier to understand may have a significant advantage in attracting first-time investors.
AI Could Become The New Financial Interface
EY’s report talks about combining India’s digital public infrastructure with AI-enabled intelligence, consent-based data sharing, scalable advice, and investor-protection mechanisms to create what it calls a “Wealth Stack.”
I find that idea particularly interesting because AI could potentially change the way people interact with financial information. Instead of asking:
“What is an SIP?”
a consumer could ask: “Explain this investment to me like I’m completely new to investing.”
Or:
“What does this number in my portfolio mean?”
Or:
“What questions should I ask before choosing an investment product?” The technology can make financial information more conversational but the need for responsible guidance doesn’t disappear If anything, it becomes more important.
The Real Opportunity Is Not 100 Million Accounts
This is where I think we need to be careful. Adding 100 million investors sounds impressive but opening an account is not the same as creating wealth.
EY itself points out that success shouldn’t be measured only through account openings or assets under management. Longer-term indicators such as investor persistence, diversification, and financial resilience matter too and I completely agree with that distinction.
The real question isn’t: “How many Indians started investing?”
It is:
“How many Indians became confident, informed, and long-term investors?” That’s a much more meaningful measure of financial inclusion.
My Takeaway
When I look at these numbers, I don’t see just an investment industry story. I see an India 2.0 consumer story.
A generation that has already adopted digital payments is now potentially moving towards digital wealth creation. The next investor may be younger.
May live outside a metro. May be a woman managing her own finances. May have started with UPI.
May have never spoken to a traditional financial adviser and may expect financial information to be as simple and accessible as everything else on their smartphone. For me, that’s the real opportunity.
India has spent the last decade making money move faster. The next decade could be about helping more Indians make their money work for the long term. and that, in my view, is a far more interesting transformation. EY India — Wealth Inclusion in India report
EY’s latest wealth inclusion report
As the industry shifts, staying informed about digital trends is essential for anyone. Click through to read another thread!